
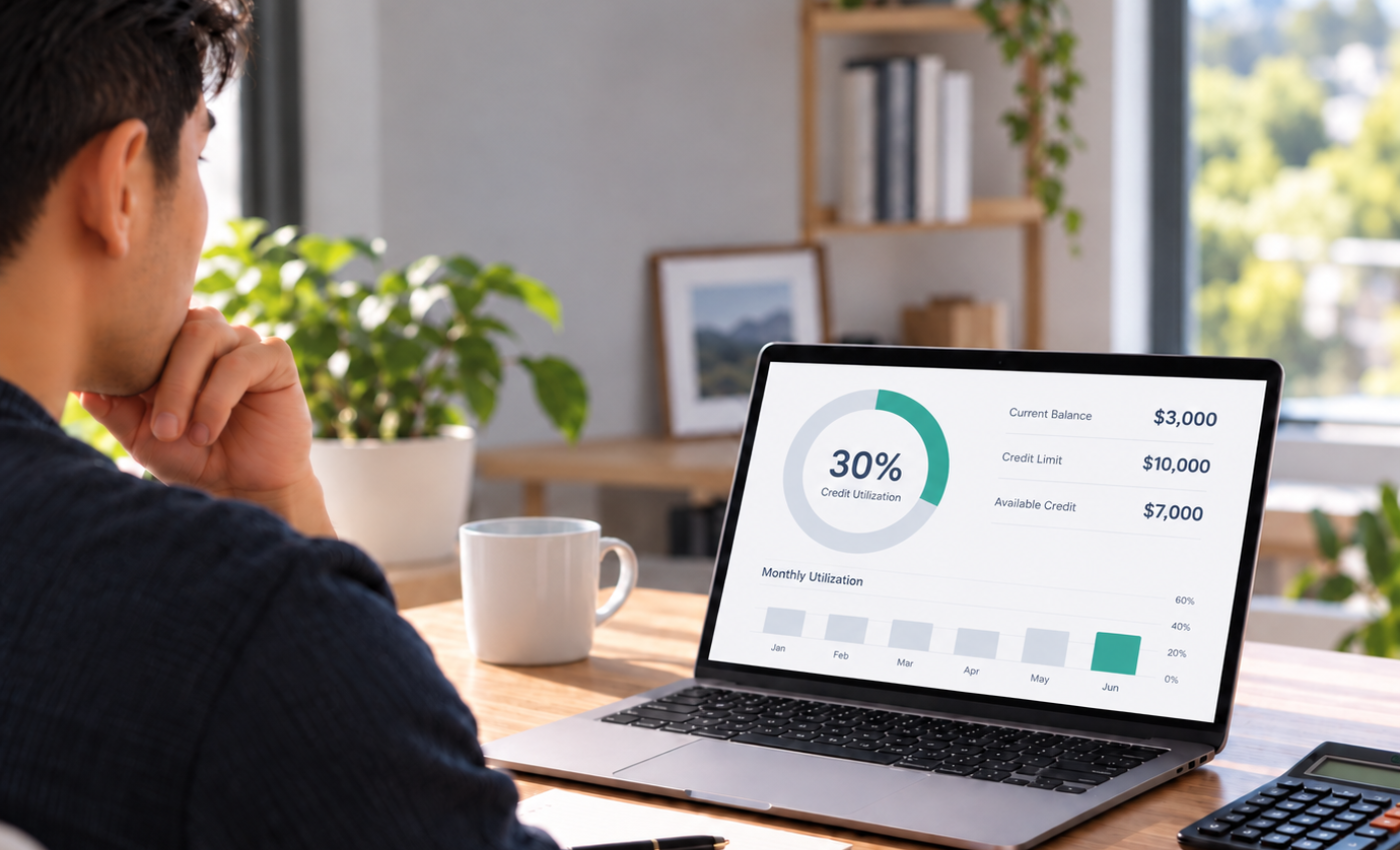
Of everything on your credit report, credit utilization is the one number you can change this month. Payment history takes years to build and years to repair. The share of your credit limit you happen to be using can move in a single billing cycle — which makes it the fastest lever most people have, and the one most often pulled the wrong way.
It is also where the most repeated advice in Canadian personal finance lives: keep it under 30%. That number is real, and it comes from the federal regulator rather than folklore. But the way it is usually explained leaves out the part that decides whether you actually hit it.
Short answer: Credit utilization is the share of your available credit you are using: divide your balance by your limit. The Financial Consumer Agency of Canada suggests staying under 30% of your total limit, but neither Equifax nor TransUnion publishes a threshold, so treat 30% as a target. Each card’s ratio counts too, and balances are usually reported around your statement date, so paying before the statement closes is the fastest fix.Key points from this guide
What Is Credit Utilization?
Credit utilization is the percentage of your available credit that you are currently using. The arithmetic is as simple as it sounds: divide the balance by the limit. Equifax uses this example — a card with a $1,000 limit showing a $300 balance is running at 30%.
Nothing about that calculation cares whether you pay the balance off a week later, whether you are carrying interest, or whether the spending was a grocery run or a flight. It is a snapshot of how much of your available credit was in use at the moment your lender reported it, and that snapshot is what lenders see.
Why Does Credit Utilization Matter So Much?
Equifax describes it as “one of the biggest factors” in a credit score, second only to payment history. The reasoning is about risk rather than morality: someone routinely using most of their available credit looks closer to their ceiling than someone using a fraction of it, and lenders read that as less room to absorb a bad month.
The Financial Consumer Agency of Canada makes the uncomfortable part explicit. Heavy use of your limit can make lenders see you as higher risk even if you pay your balance in full every month. That single clause is why a person who has never missed a payment and never paid a cent of interest can still be quietly marked down.
In simple terms: your score does not measure whether you are good with money. It measures what your file looks like on the day it is read.
Is the 30% Rule Real?
Mostly. The Financial Consumer Agency of Canada states it plainly: “Try to use less than 30% of your total credit limit.” As a federal regulator with no product to sell, that is about as clean a source as this subject offers.
What is worth knowing is that neither Equifax nor TransUnion publishes a threshold of their own. Their position is simply that lower is better, with no cliff edge at 29% and no penalty that suddenly appears at 31%. Utilization is a sliding scale, not a pass mark.
What this means for you: treat 30% as a useful target rather than a rule you have broken. Going from 80% to 45% is a real improvement even though it misses the number, and there is no prize for sitting at exactly 29%.
Does Each Card Count, or Just the Total?
Both, and this is where people get caught. Equifax confirms that “both overall credit utilization and credit utilization of individual accounts can be factored into credit score calculations” — so a healthy total can hide a problem card.
Consider someone holding three cards:
| Card | Limit | Balance | Utilization |
|---|---|---|---|
| Card A | $2,000 | $1,800 | 90% |
| Card B | $5,000 | $200 | 4% |
| Card C | $3,000 | $0 | 0% |
| All three together | $10,000 | $2,000 | 20% |
Overall utilization is 20%, comfortably inside the guideline. But Card A is maxed at 90%, and that card is visible on its own. Moving $1,000 of that balance onto Card B would leave the total completely unchanged at 20% while fixing the part that actually looks bad.
The Timing Trap Most Advice Skips
Here is the piece that undoes everything else. Your lender does not report what you owe today. It reports your balance roughly once a month, and that report usually lines up with your statement date — the day your billing cycle closes — not your payment due date.
So picture someone who puts $1,800 on a $2,000 card, waits for the statement, then pays it off in full before the due date. They carry no debt, pay no interest, and have done nothing wrong. The number that reached the bureau was still 90%, because that was the balance when the cycle closed.
Quick tip: if your utilization looks stubbornly high despite paying in full, find your statement date and make an extra payment a few days before it, not after. The balance that gets photographed is the one that counts. And since lenders may report to one bureau, the other, or both, and at different times, the two reports will not always agree — something we cover in how long information stays on your credit report.
How to Lower Your Credit Utilization
There are only three levers, and they differ a lot in speed and side effects.
Pay before the statement closes. Free, immediate, and the one most people have never been told about. It changes the reported number next cycle without changing your spending at all.
Raise the limit rather than the spending. The same $1,800 balance on a $4,000 limit is 45% instead of 90%. Scotiabank notes that asking for an increase usually triggers a hard credit check, though it also judges that the utilization benefit “should likely outweigh the impact of a hard credit inquiry.” A limit increase your bank offers you unprompted normally involves no hard check at all, which makes those worth accepting even if you never use the room.
Keep old cards open. Closing a card you no longer use removes its limit from the denominator and pushes utilization up overnight, with no change in what you owe. If the card is free to hold, the usual advice is to keep it.
What Credit Utilization Doesn’t Do
Two honest limits are worth setting against all of this. The first is that utilization has almost no memory: it is recalculated from whatever your latest reported balances are, so a bad month stops counting once the next report replaces it. That is unusually forgiving, and it is the reverse of a missed payment, which sits on your file for six years.
The second is that it is not the main event. Payment history still carries more weight than anything else, and no amount of utilization management compensates for late payments. Utilization is the fastest thing to fix, not the most important — our guide to how credit scores work in Canada sets out the full picture, and if interest is the underlying problem, how to avoid paying credit card interest is the better place to start.
Key Takeaways
- Credit utilization is your balance divided by your credit limit — $300 on a $1,000 card is 30%.
- The Financial Consumer Agency of Canada recommends using less than 30% of your total limit. Neither Equifax nor TransUnion publishes a threshold of its own, so treat it as a target, not a pass mark.
- Heavy use can mark you down as higher risk even if you pay in full every month.
- Both your overall ratio and each individual card count, so a maxed card can hurt even when your total looks healthy.
- Lenders report your balance around your statement date, not your due date — paying in full after the cycle closes can still report high utilization.
- Paying before the statement closes is the fastest fix. Raising a limit helps but usually costs a hard check; closing an old card pushes utilization up.
- Utilization resets with each new report, so a bad month does not follow you the way a missed payment does.
This article is for general educational purposes and isn’t financial advice. Credit scoring models are proprietary and the weight given to any single factor varies between Equifax, TransUnion and individual lenders — confirm current guidance with the bureaus or the Financial Consumer Agency of Canada. Figures were checked in September 2026.